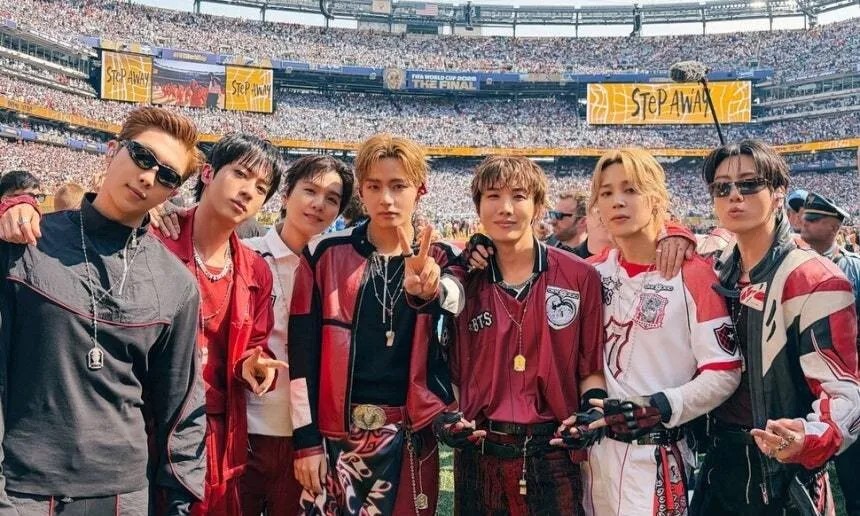
In a paradoxical turn of events for the K-pop giant HYBE, the company is currently staring down the barrel of record-breaking financial forecasts while simultaneously seeing its stock price stumble. Despite analyst projections estimating a massive revenue surge to over 5 trillion won—an staggering 93.2% increase from the previous year—and operating profits nearing 300 billion won, the market response has remained tepid. For global fans and casual observers alike, this creates a confusing narrative: if the business is more profitable than ever, why does the stock market seem hesitant to embrace the momentum? The answer lies in a complex shift in investor sentiment regarding the entertainment industry, the long-term sustainability of legacy acts, and the strategic pivot toward a multi-artist roster.
To understand the current tension, we must look at the broader industry climate. Market analysts, such as Park Jun-hyung from SK Securities, have pointed to a phenomenon known as ‘industry derating.’ This is where investors lower the valuation multiple of an entire sector, regardless of a single company’s stellar performance. This adjustment reflects a more cautious approach to entertainment stocks globally, as investors weigh the volatile nature of celebrity-driven revenue against rising operational costs. For fans who view HYBE primarily as a creative powerhouse, this serves as a stark reminder that the corporate machine operates on a different, often colder, mathematical logic than the emotional connection felt by the fandom.
Why Is the Stock Price Under Pressure Despite Record Growth?
A primary question fans often raise when seeing news of financial success alongside stock drops is whether the company is truly ‘failing.’ The reality is far more nuanced. The recent dip in HYBE’s stock reflects a recalibration of expectations. Analysts have applied a more conservative price-to-earnings ratio (PER) to account for this sector-wide derating. Essentially, even as HYBE’s absolute numbers climb, the premium that investors are willing to pay for each unit of profit has tightened. It is an industry-wide sentiment that suggests investors are no longer looking just at ‘top-line’ revenue growth, but are scrutinizing the long-term scalability of the company’s dependency on specific IPs.
What Is the ‘BTS Factor’ and Why Is It Still So Critical?
Even with the company’s diversification efforts, the BTS shadow remains a pillar of their valuation. Analysts note that the return of BTS to world touring is a massive driver for future revenue. However, there is a clear strategic imperative to lower the company’s total reliance on the group. The 2024 financial projections suggest that while BTS is expected to drive massive ticket sales in North America and Europe, the profit margins for these tours require a fine balancing act. The initial heavy lifting of tour production costs can compress profit margins, though these are expected to stabilize as the tours progress. The ‘BTS effect’ is not just about direct ticket sales; it is about the leverage the group provides in negotiations with global promoters, a benefit that cascades down to every other artist under the HYBE umbrella.
How Are Newer Groups Changing the Profitability Model?
Perhaps the most vital shift in HYBE’s trajectory is the speed at which it now cultivates new talent. Analysts have observed that the network and infrastructure built for global superstars like BTS are now being utilized to slash the time it takes for new acts to enter the North American market. Where previous generations of K-pop artists might have spent nearly three years establishing a foothold, HYBE’s newer IPs are doing it in roughly 16 months. This is a massive shift in efficiency. Groups like SEVENTEEN (whose recent activities continue to provide a foundation) and rising, younger acts are beginning to contribute significantly to the bottom line. By leveraging existing infrastructure, HYBE is seeing a higher return on investment from these younger groups, as they move past their initial high-cost debut phases into highly profitable growth periods.
What Does the 2027 Outlook Reveal About Industry Strategy?
The long-term strategy for HYBE seems to be a transition toward higher profit margins despite the potential for fluctuations in total revenue. Analysts project that by 2027, even if raw revenue figures see a slight dip—depending on the specific activity level of legacy artists—the actual operating profit margin will likely improve. This is the ‘holy grail’ of corporate strategy: doing more with less. By shifting the internal business mix toward younger artists who are currently in favorable contract cycles, HYBE aims to build a more robust, diversified machine. For the fan community, this is a double-edged sword; while it promises stability for the company, it also signals a transition away from the era where a single act dictated the entire fiscal year.
Ultimately, the current market sentiment toward HYBE is not a vote against the music or the artists themselves, but a reflection of a maturing K-pop market. As the industry moves away from ‘hyperspeed growth’ and toward ‘sustainable profitability,’ the pressure on companies like HYBE to prove that their new talent can sustain the company’s valuation is only increasing. For global fans, the takeaway is clear: the success of the music and the success of the stock are now increasingly decoupled. As we look ahead, the real test for HYBE will be whether these newer groups can command the same level of global cultural resonance as the legacy acts that built the company, thereby validating the analysts’ hopes for a more efficient, diversified future. The numbers suggest the foundation is there, but the market is clearly waiting for the proof of concept to reach full maturity.